PCP vs HP car finance: which costs less, with a worked example
Walk into almost any car dealer and the first number you’ll hear is a monthly payment. That’s deliberate. A low monthly figure makes a car feel affordable, and it moves your attention away from the number that actually matters: how much the car will cost you in total.
Most car finance in the UK is either PCP or Hire Purchase. They work very differently, and the cheapest monthly payment is rarely the cheapest deal.
Hire Purchase: simple, and you own the car
With Hire Purchase (HP), you pay a deposit, then fixed monthly payments that cover the whole price of the car plus interest. After the last payment, often with a small “option to purchase” fee, the car is yours. There’s no big payment at the end and no mileage limit.
The downside is that monthly payments are higher, because you’re paying off the entire car over the term.
PCP: lower payments, with a catch
Personal Contract Purchase (PCP) splits the cost differently. The lender estimates what the car will be worth at the end of the deal, called the guaranteed future value or balloon payment, and your monthly payments only cover the difference. So the payments are much lower.
At the end you have three choices: pay the balloon and keep the car, hand it back and walk away, or use any value above the balloon as a deposit on another car. If you hand it back, it has to be within the agreed mileage and in good condition, or you’ll pay extra charges.
The catch is that you pay interest on the whole amount you borrowed, including the balloon, for the entire term. That’s why PCP usually costs more in total if you keep the car.
The same car, three ways
I put a £20,000 car with a £2,000 deposit over four years through our car finance calculator, at a typical dealer rate of 9.9% APR, and compared it with a personal loan at 6.9%.
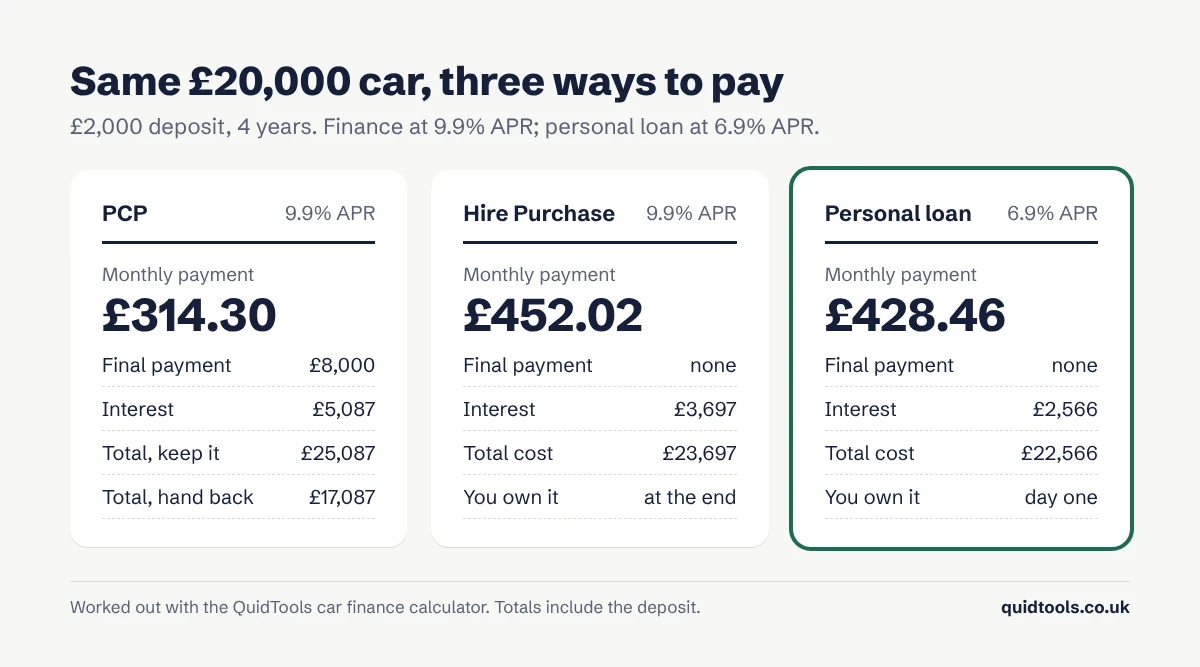
PCP has the lowest monthly payment by a long way, at £314 against £452 for HP. But if you want to keep the car, PCP costs about £1,400 more than HP, because of the extra interest on the balloon. A personal loan at a lower rate beats both, and you own the car from day one.
PCP does make sense in one situation: if you like changing your car every few years and would hand it back anyway. Then you’re only paying for the part of the car you used, which is the £17,087 figure.
Always compare the APR
The APR is the true yearly cost of borrowing, including fees. Some dealers also quote a “flat rate”, which looks lower because it’s worked out on the original amount you borrowed for the whole term, even though your balance falls as you pay. A 5% flat rate is roughly a 9.5% to 10% APR. Always compare deals using the APR.
Two rights worth knowing
You can end the deal early. On both HP and PCP, you have a legal right to hand the car back once you’ve paid half of the total amount payable, including the balloon on PCP. This is called voluntary termination, and it can be a lifeline if your circumstances change.
You can settle early. You can pay off the finance at any time, and the lender has to knock off the interest you haven’t used yet. Ask for a settlement figure.
Run your own deal
Our car finance calculator compares PCP, HP and a personal loan for the same car, using the APR, and marks the cheapest. If you already have a deal and want to pay it off faster, the loan overpayment calculator shows how much interest you’d save.
This is general information, not financial advice. The figures are an example; your own deal depends on the lender, your credit record and the car. Check the APR and total amount payable on any finance quote before you sign.